Buying Your First Home in South County San Diego: Where to Start
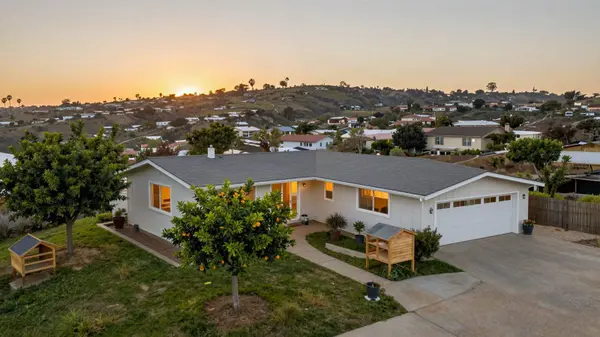
It usually starts at 11 p.m. on a phone. You're in bed, scrolling listings you swore you'd stop looking at. There's a three-bedroom in Chula Vista with a lemon tree and a kitchen that's actually nice. You screenshot it. You send it to your partner, who's asleep next to you. Then the real question hits: could we actually buy this?
Almost every first-time buyer we meet has been in that moment. The listings are the fun part. The real work happens before you ever book a showing, and it's a lot less scary when someone walks you through it.
Here's how we do it, step by step, for buyers in Chula Vista, National City, Bonita and the rest of the South County.
Step 1: Talk to a lender before you fall in love
A pre-approval tells you three things: how much you can borrow, what your monthly payment would be and which loan programs fit you. In a competitive market, sellers expect to see one attached to every offer. Without it, your offer goes to the bottom of the pile.
Ask your lender to compare a few options side by side:
- Conventional loans, with as little as 3% down for some first-time buyers.
- FHA loans, with 3.5% down and more flexible credit requirements.
- VA loans, with no down payment for eligible veterans and service members. With the Navy bases next door, this is one of the most common loans we see in the South Bay.
Step 2: Ask about down payment help
There's real money out there for first-time buyers, but the rules depend on where you buy.
- CalHFA programs are available statewide for buyers who meet income and credit limits. The Dream For All program can cover up to 20% of the price, but it runs as a once-a-year lottery, and the 2026 round closed in March.
- San Diego County's Down Payment and Closing Cost Assistance program offers deferred loans to qualifying buyers. It only covers homes in unincorporated areas like Bonita and Spring Valley, plus a list of smaller cities. Chula Vista, National City and El Cajon aren't on that list, so ask those cities about their own programs.
Funding opens and closes, and most programs require a homebuyer class. Your lender should know which ones are open right now.
Step 3: Budget for the real payment, not the price
The list price is only part of the story. Before you compare homes, add up:
- Property taxes: in California, roughly 1% of the purchase price, plus any local assessments.
- Mello-Roos: a special tax common in newer communities like Otay Ranch and Eastlake. It can add hundreds of dollars a month.
- HOA dues: for condos, townhomes and many newer neighborhoods.
- Homeowners insurance: get a quote early, especially near open hillsides.
- Closing costs: often 2% to 5% of the price, on top of your down payment.
Two homes with the same price can have monthly payments hundreds of dollars apart. It's the most common surprise we see, and the easiest one to avoid. We ask for the Mello- Roos and HOA numbers before we write any offer.
Step 4: Pick your top two
Most first-time buyers end up choosing between size, location, condition and price. Write down your top two before you tour anything. It keeps you from falling for a house that misses on what matters most.
A few honest tradeoffs here in the South County:
- Condos and townhomes are often the most affordable way in, but HOA dues and rules vary a lot. If you're using FHA, the complex usually needs to be FHA-approved.
- Older homes on Chula Vista's west side and in National City can come in at lower prices with no Mello-Roos, but often need some work.
- Newer homes on the east side need less work but usually cost more each month.
Step 5: Make an offer you can stand behind
When you find the one, we'll pull recent comparable sales so you know what the home is actually worth, not just what it's listed for. Then we'll build an offer that's strong without giving away protections you need.
In California, offers usually include contingencies for the loan, the appraisal and inspections. They're your safety net. Don't waive them without understanding exactly what you're risking.
Step 6: Inspect, then celebrate
Once your offer is accepted, the clock starts. You'll schedule the inspection, review the seller's disclosures and work with your lender on the appraisal and final approval. Most purchases close in about 30 days.
The inspection report will look long and scary. That's normal. Some items are just what comes with an older home; others are worth negotiating. We'll help you tell the difference. Then one day, you'll be sitting on the floor of an empty living room, holding a set of keys that are actually yours.
Ready to start?
Buying your first home doesn't have to be overwhelming. We'll explain every step in plain language and never rush you. Call us for a no-pressure conversation about where you are now and what it would take to get you home.
Talk to Team RatcliffeTeam Ratcliffe | Coldwell Banker West
Pamela Ratcliffe, CA DRE #01152227 (619) 981-5606 · pam@teamratcliffe.com
This post is general information, not financial or legal advice. Program rules and funding change often, so confirm details with your lender.
Categories
Recent Posts
GET MORE INFORMATION